Research
The legal entity on the contract is the firm you have
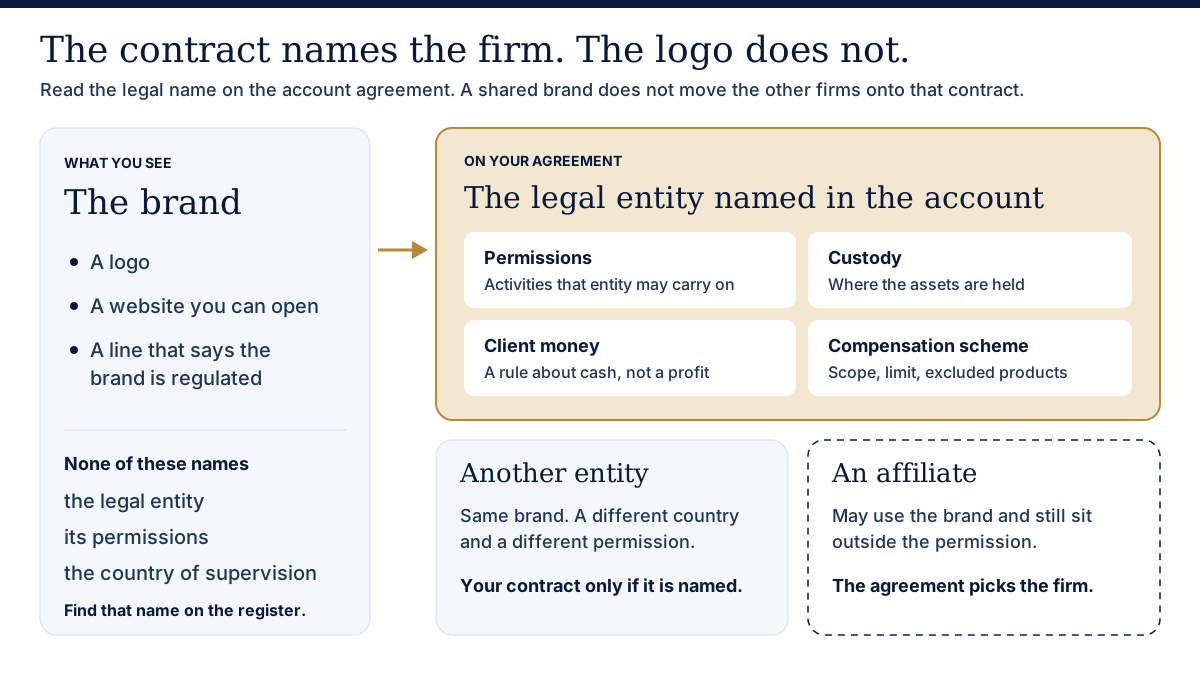
A logo is not a regulator. The firm you contract with is a legal entity, supervised where it is supervised, for the activities on its permissions. A sentence that says the brand is “regulated” has not named the entity or the permission.
Key points
- Permissions, custody and any compensation scheme are entity-specific and country-specific.
- Client money segregation is a rule about cash, not a promise that a trade will make money.
- A group can contain a supervised broker and an unsupervised affiliate. The contract says which one you have.
What is going on
Stock brokers, investment platforms, foreign-exchange dealers, futures commission merchants and event-contract venues sit under different statutes. Some hold client assets at a custodian. Some are the counterparty to the trade. A compensation scheme, where one exists, has a scope, a limit and a list of excluded products. Those limits are not interchangeable between the United States, the United Kingdom, the European Union and Australia, and they are not interchangeable between entities in one group.
Why it matters
Counterparty risk is the risk that the firm on the other side of the contract does not pay. Custody risk is the risk that the assets are not where the statement says they are. Both can be present. A permission to sell investments is not a judgement that the firm’s products are suitable for you. WiT Markets does not treat a generic “regulated” badge as equivalent across countries, and it does not invent a licence number that was not read from a register.
What to watch
Read the legal name on the account agreement and find that name on the register of the authority that is claimed. Note the permissions, and note what is outside them. If the page you are reading is a marketing site for several entities, assume nothing about your own eligibility until the application names the entity. The country pages on this site, where they are published, are the place for local protection rules.
Risks
Registers lag. A firm can be authorised and still fail. A scheme can refuse a claim that falls outside its rules. This note is not a check of any named firm’s current permissions. Named comparisons on WiT Markets stay unpublished where the fee and entity record is not confirmed.
Related
Sources and review
Written by: WiT Markets Editorial. Writes and structures WiT Markets pages. Separates a sourced fact from a cell that is Not confirmed.
Review: Editorially reviewed. This is not a qualified specialist review and it is not a legal sign-off.
Last reviewed: . Next review due . The date is an editorial pass. It is not a live check of every third-party fee.
Regulatory and official sources
- Financial Conduct Authority — checked 13 October 2026
- U.S. Securities and Exchange Commission — checked 13 October 2026
- Investor.gov — checked 13 October 2026
Other sources
- WiT Markets methodology — checked 13 October 2026
Methodology. Editorial policy. Corrections. Report an error.